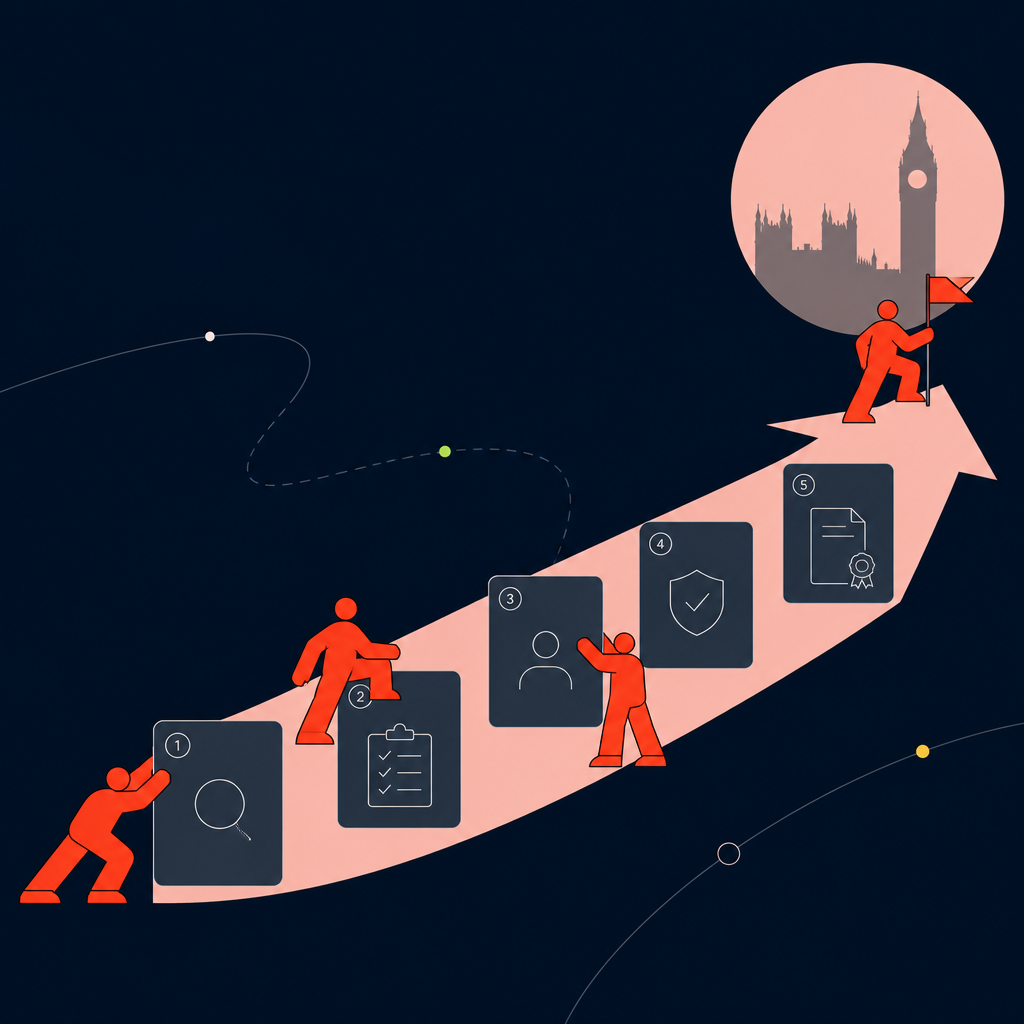
A growing company decides it needs someone working in the UK this quarter, not next year. There's no UK entity, no PAYE registration, no local bank account for payroll, and legal is already warning that setting one up could take three to six months. This guide walks through the exact sequence for onboarding that UK hire through an Employer of Record correctly the first time, including the classification and worker-record decisions that turn a fast fix into a compliance problem six months later.
Why an entity isn't the answer for your first UK hire
Setting up a UK entity means registering with HMRC and Companies House, opening a payroll scheme, and hiring local counsel before a single contract is signed, and that process runs in months, not weeks. An Employer of Record lets a company employ someone in the UK almost immediately by using the provider's existing legal entity instead of building one from scratch.
That works because of what an Employer of Record actually does under the hood: it acts as the legal employer for tax, payroll and compliance purposes, handling registration, payroll processing and statutory filings so the hiring company can direct the work without owning the entity risk.
That distinction is why EOR has become the default entry point for companies testing a new market before committing capital to a subsidiary. The UK is already far along that curve: it holds close to a 9% share of the European Employer of Record market, pushed up by international business activity and the shift to remote hiring, which means UK EOR is a well-established route with real competition among providers rather than a niche workaround.
None of that removes the classification questions once a worker is actually onboarded, which is where the process below starts to matter.
What you need before you engage an EOR in the UK
Before running the steps, gather what the process actually requires. A hiring manager needs a handful of concrete inputs ready, or the provider will bounce the case back for clarification and cost the company the timeline advantage it was trying to gain in the first place.
Before contacting a provider, gather:
- The worker's full details and target start date
- A written role scope and reporting line
- An internally approved budget that covers salary plus the provider's margin
- A named internal approver for the contract
- A preliminary view on employment status: does this look like employment or genuine contractor work
- If relevant, the paper trail on any existing contractor arrangement with this person
Skipping that classification question is the most common reason UK EOR onboarding stalls halfway through. Providers will decline or delay a case where the facts already point to an employment relationship, no matter what the internal paperwork calls it.
Step 1: Decide if EOR is even the right route for this hire
With prerequisites gathered, the first real decision is the routing question, and it has to happen before any provider conversation. Routing a genuine contractor through an EOR, or routing what's actually an employee through a contractor agreement, creates the same classification exposure a company is trying to avoid in the first place.
UK tax authorities look at control, substitution rights, integration into the business and financial risk. A worker who takes instructions daily, uses company equipment and has no right to send a substitute looks like an employee regardless of what the contract calls them.
Employee, EOR, or contractor: how to tell which applies
The practical test is simple to describe even if the judgment calls aren't. If the person works set hours, reports to a manager, uses the company's tools and can't send someone else to do the job, that's employment, and EOR is the correct route.
If they set their own hours, use their own equipment, carry commercial risk and could substitute another worker, that's genuine contractor work, and it belongs in a contractor engagement model instead of EOR.
The genuinely uncertain middle ground needs a structured classification review before any contract is signed, not after.
Step 2: Choose and vet an EOR provider for the UK
Once EOR is confirmed as the right route, the next decision is who runs it. Choosing a provider is where most of the actual risk transfer happens, because the EOR is the entity legally on the hook for UK employment law, tax withholding and statutory benefits.
If it gets those wrong, the exposure can still land back on the hiring company's reputation and timeline even when it isn't the company's legal liability. A provider that operates its own licensed UK entity, rather than subcontracting through a local partner, is easier to hold accountable and faster to fix when something goes wrong. This is also where financial control sits: the provider invoices for salary plus its margin, and the company needs clean visibility into that spend from month one, not a reconciliation exercise later.
Questions to ask about UK payroll operation
Before signing, ask each shortlisted provider:
- Does it run UK payroll through its own entity or through a subcontracted local partner
- How does it handle PAYE tax codes, National Insurance and pension auto-enrolment in practice
- What happens to the worker's contract and pay if the provider loses its UK registration or exits the market
- How does it store and share worker records, and does that meet UK data protection requirements
- What's the actual notice period and exit process if the company needs to move the worker to its own entity later
A provider that can't answer the exit-process question clearly is one to avoid, and it's usually the same provider that can't produce clean records six months in.
Step 3: Onboard the worker and set up UK-compliant payroll
With a provider selected, execution is the next hurdle, and it follows a fixed sequence regardless of provider. UK employment law sets specific deadlines for some of these steps, and skipping the order creates gaps a worker will notice on day one, usually in their first payslip.
The provider handles a fixed sequence of onboarding tasks:
- Issues an employment contract under UK law
- Runs a right-to-work check before the start date
- Collects a P45 or completed starter checklist to set the correct tax code with HMRC
- Enrolls the worker in its pension scheme within the statutory auto-enrolment window
- Briefs the worker on statutory sick pay and holiday entitlement
- Adds the worker to the first payroll cycle
UK payroll typically runs monthly, so timing the start date against the provider's cutoff avoids a first payslip that's late or wrong. The hiring company's job through this stage is mostly to confirm details fast: a delayed sign-off on the contract or a missing document is the most common reason a land date slips past the date the business actually needed the person working.
Step 4: Build the worker record so it survives an audit
Onboarding is live, but the record it leaves behind is what scales. A single UK hire generates a contract, a payroll record, a right-to-work check, a pension enrollment confirmation and, when the provider runs its own UK entity, statutory filing confirmations from HMRC. That paper trail is what a regulator or an internal auditor asks for first, and it's also what the company needs on hand if it later moves the worker onto its own payroll.
A complete UK worker file should include:
- Signed employment contract and any amendments
- Right-to-work check and supporting documents
- P45 or starter checklist and current tax code
- Pension auto-enrolment confirmation, and opt-out records where they apply
- Monthly payslips and year-end P60
- Statutory sick pay and holiday entitlement records
Ask the provider up front how it stores these records and how fast it can produce them on request. A provider that takes weeks to pull a right-to-work check or a payslip history isn't giving the company audit readiness, it's giving it a filing cabinet with someone else's lock on it. Workforce visibility matters here too: once a company scales past one or two UK hires, HR needs a single view of who's employed through the EOR, what they cost, and when contracts renew, not a folder of PDFs scattered across email threads.
Troubleshooting: common issues when setting up EOR in the UK
Most problems with UK EOR onboarding trace back to a handful of recurring issues, and nearly all of them are avoidable if caught early rather than discovered mid-process.
- Contract sign-off delays. A missing internal approver stalls onboarding even after the provider is ready. Name the approver before onboarding starts, not during it.
- Misclassification surfaces late. If a "contractor" relationship looks like employment once the standard tests are applied, the provider may pause or reclassify the engagement mid-onboarding. Run the classification check in Step 1, not after the contract is drafted.
- Payroll cutoff missed. Starting a worker a few days after the provider's monthly cutoff pushes their first payslip out by a full cycle. Confirm the cutoff date before agreeing to a land date.
- Records scattered across systems. Some providers keep contracts in one system and payroll in another, which slows down any audit request. Ask for a single worker record before signing.
- No clear exit path. If a provider is vague about what happens to the worker's contract when the company ends the relationship or moves them to its own entity, treat that as a warning sign rather than a detail to sort out later.
The company that started this process needing someone in the UK this quarter doesn't need a UK entity to get there. It needs the classification call made correctly, a provider that owns its UK entity and can produce records on demand, and a worker file that holds up if HMRC or the company's own auditors ever ask to see it. Skip any one of those and the EOR route stops being the fast, compliant option it was chosen for.
The next step is global hiring & contractor compliance in your own setup
Bring your countries, worker mix and payment cycles to a Papaya specialist and get a straight answer on what changes.